The Cash Flow
Crux of
Agribusiness
Managing the intense liquidity gap between planting season expenses and post-harvest sales, because more farms fail from illiquidity than from unprofitability.
One of the most dangerous financial misconceptions in agriculture is the belief that a profitable farm is automatically a financially healthy farm. More commercial farms are brought down by illiquidity than by structural unprofitability. On paper, an agricultural enterprise can show strong multi-million naira net income projections based on high harvest yields and favorable market prices. Yet, despite holding a highly profitable crop or livestock line, the venture can suddenly face a mid-season cash crisis that halts operations before a single bag of produce reaches the buyer.
The reason is simple: profit and cash are not the same thing. A farm can have strong projected margins, attractive annual profits, valuable biological assets, and a growing customer base, and still be unable to pay its workers, purchase fertilizer, buy feed, service a loan, or settle a supplier invoice next month. Agriculture creates an unusually difficult timing problem because expenditure occurs long before revenue. The farm spends continuously during the biological growth cycle, while receiving nothing in return until harvest.
→ Feed & fertilizer
→ Land preparation
→ Fuel & labor
→ Irrigation & energy
Revenue: ₦0
→ Off-take payouts
→ Working capital replenished
Revenue: Arrives in full
Section 01
Profit Is Not Cash —
The Core Distinction
This disconnect occurs for three structural reasons. Timing mismatch: a buyer’s promise to pay ₦50 million after harvest does not provide the liquid cash needed to buy diesel today. Capitalized biological expenses: accounting rules often capitalize early inputs into biological inventory value rather than counting them as immediate cash losses, the income statement looks profitable while the bank balance drains. Reinvestment cycle: even when a farm generates cash from an early harvest batch, management often immediately reinvests into the next cycle’s inputs, leaving zero liquid reserve.
The cash flow trough is the most important number in agricultural finance. If a farm begins the season with ₦60M in available cash and the projected cumulative cash deficit before harvest reaches ₦85M, the business has a ₦25M funding gap, even if it eventually generates ₦70M in operating profit. That forecast must be built before planting begins, not after the bank account runs critical.
Section 02 — Case Study
Cash Flow Dynamics at
JILOW Agro Operations
A seasonal cash flow model built by the JILOW Agro AgriFinance division for a 100-hectare commercial production layout: six-month production cycle, ₦50M initial working capital, ₦90M projected harvest sales, ₦60M total direct expenses, projecting an attractive ₦30M net profit. Despite these strong financials, a monthly cash flow audit revealed a severe liquidity trough.
| Month | Activities | Inflows | Outflows | Closing Balance | Status |
|---|---|---|---|---|---|
| M0 | Capital allocation & cash setup | ₦50,000,000 | ₦0 | ₦50,000,000 | Fully capitalized — opening reserve ready |
| M1 | Tillage, seed/stocking, starter feed | ₦0 | ₦18,000,000 | ₦32,000,000 | High outflow — heavy upfront inputs |
| M2 | Intensive feeding, weeding, energy | ₦0 | ₦15,000,000 | ₦17,000,000 | Sustained burn — past 60% of opening capital |
| M3 | Mid-cycle inputs, water management | ₦0 | ₦14,000,000 | ₦3,000,000 | CRITICAL TROUGH: Near zero — default risk on feed bills |
| M4 | Pre-harvest maintenance, labour | ₦0 | ₦8,000,000 | −₦5,000,000 | INSOLVENCY WITHOUT CREDIT LINE: Operations halt if unfunded |
| M5 | Harvest initiation & packaging | ₦15,000,000 | ₦5,000,000 | ₦5,000,000 | Early relief — initial off-take stabilizes position |
| M6 | Final off-take settlement | ₦75,000,000 | ₦0 | ₦80,000,000 | Profitable recovery — net profit realized |
The critical insight: a farm projecting ₦30M net profit faces a ₦5M cash deficit at Month 4, before a single naira of harvest revenue has materialized. Left unaddressed, the Month 4 deficit halts feeding schedules, which stresses or kills the biological assets, which destroys the harvest that was supposed to deliver the profit. The farm fails not because it was unprofitable, but because it ran out of cash before the profit arrived.
The Three-Part Liquidity Protection Strategy
Structured Supplier Credit — Net-60 Feed Terms
30% of feed supplied on Net-60 payment terms, deferring a significant portion of the largest single cost category beyond the point at which harvest revenues have begun to arrive. Secured before stocking, not after the crisis materializes.
Revolving Working Capital Line — ₦10M Standby Credit
A pre-arranged ₦10M standby credit facility locked in before planting, not applied for during the crisis. Eliminates the Month 4 deficit entirely and preserves management’s negotiating position. Arranged when the business looks strong, not when it looks desperate.
Staggered Cohort Harvesting — Early Off-Take at Month 4
A structured partial harvest initiated in Month 4 generating early off-take revenue before the full harvest. Converts an illiquid near-harvest asset into cash at the precise moment of maximum liquidity need, without compromising the biological cycle of the remaining cohort.
The critical principle demonstrated by this case: all three mechanisms were arranged before the trough arrived, not after it was reached. Financing negotiated in anticipation is planned; financing negotiated in desperation is punitive. The difference is 60 days of foresight.
Section 03
The Three-Part Cash Flow
Management Framework
Section 04
Scenario Planning —
Never Rely on One Projection
Agricultural cash forecasts must model adverse scenarios, not only the expected outcome. The purpose is not to identify the worst-case and refuse to proceed, it is to determine whether the business remains solvent under reasonable adverse conditions, and to identify in advance what financing bridges a severe trough without forcing production compromises that make the outcome worse.
| Scenario | Conditions Modelled | Management Question Answered |
|---|---|---|
| Base Case | Expected production, normal mortality/yield, projected input prices, standard payment timing | Does the operation remain solvent on current financing under normal conditions? |
| Downside Case | Higher input costs, lower selling prices, slightly delayed buyer payments | How much additional credit headroom is needed to absorb moderate adverse conditions? |
| Severe Case | Production disruption, delayed harvest, lower yields, significant buyer payment delay, input price spike, simultaneously | What is the minimum liquidity reserve that keeps the business alive through a worst-case cycle? |
Section 05
The Eight-Indicator
Cash Flow Dashboard
For operational management, a rolling 13-week cash forecast provides substantially greater liquidity visibility than an annual budget alone, updated weekly so that if an expected customer payment moves from Week 6 to Week 10, management immediately sees the downstream effect on every subsequent week’s balance and can act before the gap becomes critical.
| Indicator | What It Reveals |
|---|---|
| Opening Cash Balance | How much liquid cash is available today to fund operations |
| Projected Minimum Cash Balance (Trough) Critical | The lowest expected cash position during the production cycle, the single most important number in agricultural finance |
| Cash Runway Critical | How many weeks or months the business can operate before additional funding is required |
| Operating Cash Flow | Whether the core business is generating or consuming cash from its primary activities |
| Receivables Days | How quickly customers are converting invoices into cash, a lagging buyer payment is a hidden liquidity drain |
| Payables Days | How quickly suppliers must be paid, whether payment terms match harvest timing |
| Working Capital Requirement Critical | The total capital needed to finance the production cycle from stocking through to off-take |
| Funding Gap Critical | How much additional financing is required to bridge the trough without production compromise |
These indicators should sit alongside production KPIs, feed conversion ratios, mortality rates, growth rates, rather than inside a separate finance silo. The decision to delay a feeding schedule by one day to preserve cash has a direct biological consequence. Cash flow management is production management.
Section 06
Three Operational Rules for
Agribusiness Liquidity
Critical Thinking
Why Can a Farm Show Strong Net Profit
While Being Cash-Broke?
Because the income statement and the cash flow statement measure fundamentally different things, and both can be accurate simultaneously.
Suppose a farm sells ₦200 million of produce on credit. Under accrual accounting, the sale is recognized as revenue immediately, it appears on the income statement as income, generating a strong net profit. But if the customer has 90 days to pay, the ₦200 million has not entered the bank account. The farm has an accounting profit and a liquidity problem at the same time. Meanwhile, the farm has already paid for seed, fertilizer, feed, labor, fuel, and transport in cash. Cash has left the business; the corresponding inflow has not yet arrived.
The same phenomenon occurs when cash is tied up in biological assets. A growing crop increases the economic value of the business without increasing the bank balance at all. A farm with ₦80 million worth of near-harvest fish in its ponds and ₦2 million in its bank account is simultaneously profitable and illiquid. The ₦80 million in the ponds cannot pay next week’s feed bill.
For farm management, this distinction carries a specific and practical implication. Three financial conditions can coexist in the same agribusiness at the same moment: strong accrual profitability on the income statement, significant biological asset value on the balance sheet, and insufficient cash to meet next month’s operational obligations. The income statement and the balance sheet will look healthy. The cash flow statement will tell a different story. Managers who review only the former two will be surprised by the crisis that the latter predicted.
Conclusion
Profitability Determines
What the Business Can Make
Agriculture has a unique financial rhythm. Money leaves the business during planting. More money leaves during production. The crop grows. Management waits. Then, eventually, harvest converts months of biological investment into saleable inventory, and, if collections are timely, into cash. The danger lies in the gap.
Professional agribusiness management requires both dimensions simultaneously. The income statement tells management whether the enterprise creates economic value. The cash flow statement tells management whether the enterprise can survive long enough to collect that value. The strongest farm operators understand this distinction at the beginning of every production cycle, not after the crisis has arrived. They forecast the trough before planting. They negotiate financing before they need it. They monitor collections before invoices become overdue. They protect critical working capital as a strategic production input, not merely an accounting outcome.
Profitability determines how much money the business can ultimately make.
Liquidity determines whether the business reaches harvest day.
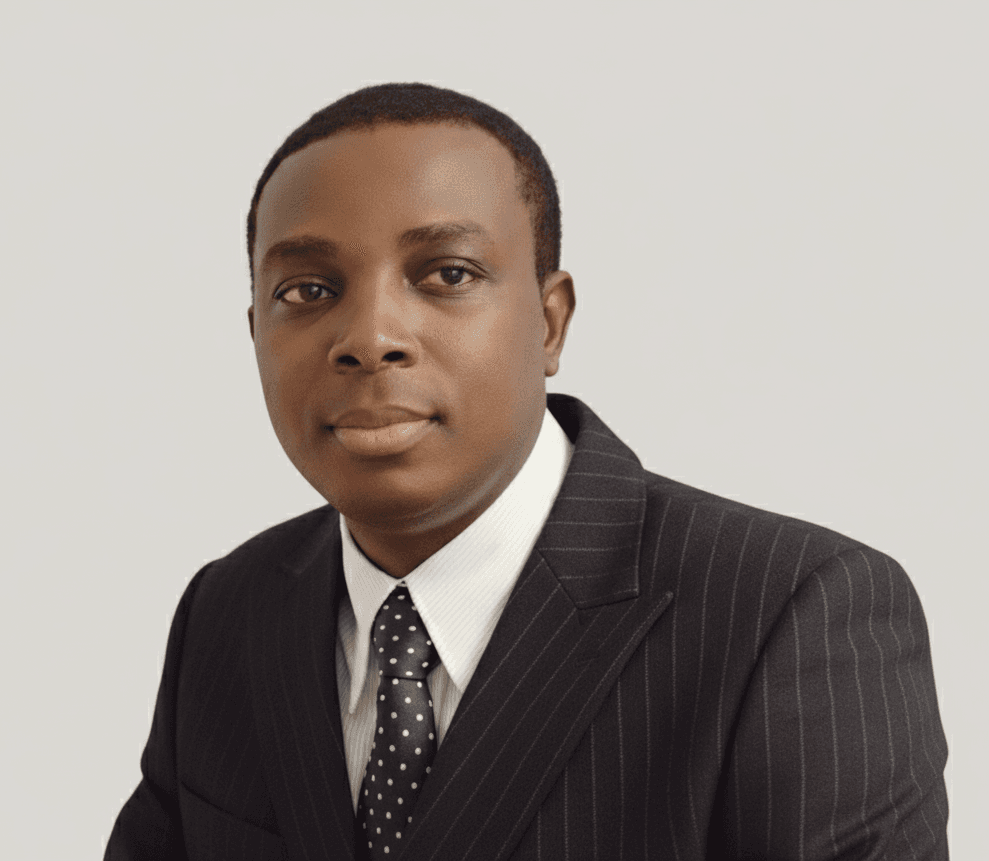
Enyo Ukwela holds an MSc in Aquaculture and Professional Certificates in Project Management and Data Analytics. He is the founder of JILOW Agro (a division of JILOW Horizon Ventures Limited), an integrated agro-industrial enterprise providing agricultural consultancy, project management, talent, data intelligence, and technology solutions across the African agribusiness sector. He writes about aquaculture, agribusiness strategy, leadership, data analytics, AI automation, and business transformation.